What 90% of MSMEs Misunderstand About Working Capital Cycles
For many MSMEs, business performance is often measured by sales growth, increasing orders, or yearly profits. Yet, despite healthy revenues and a growing customer base, thousands of businesses continue to struggle with delayed salaries, supplier pressure, unpaid EMIs, and constant cash shortages.
Why does this happen?
The answer lies in one of the most misunderstood financial concepts in the MSME ecosystem — the Working Capital Cycle.
Many business owners assume that if sales are increasing, financial stability will automatically follow. In reality, profits on paper and actual cash availability are two completely different things.
A business can be profitable and still run out of money.
Understanding how working capital moves through the business is no longer optional for MSMEs. In today’s competitive and fast-moving market, managing liquidity efficiently often matters more than simply increasing revenue.
Understanding Working Capital in Simple Terms
Working capital is the money required to manage the day-to-day operations of a business.
It includes:
Purchasing raw materials
Paying salaries and rent
Managing inventory
Handling operational expenses
Paying suppliers
Managing receivables from customers
In simple words:
Working capital is the fuel that keeps a business running every day.
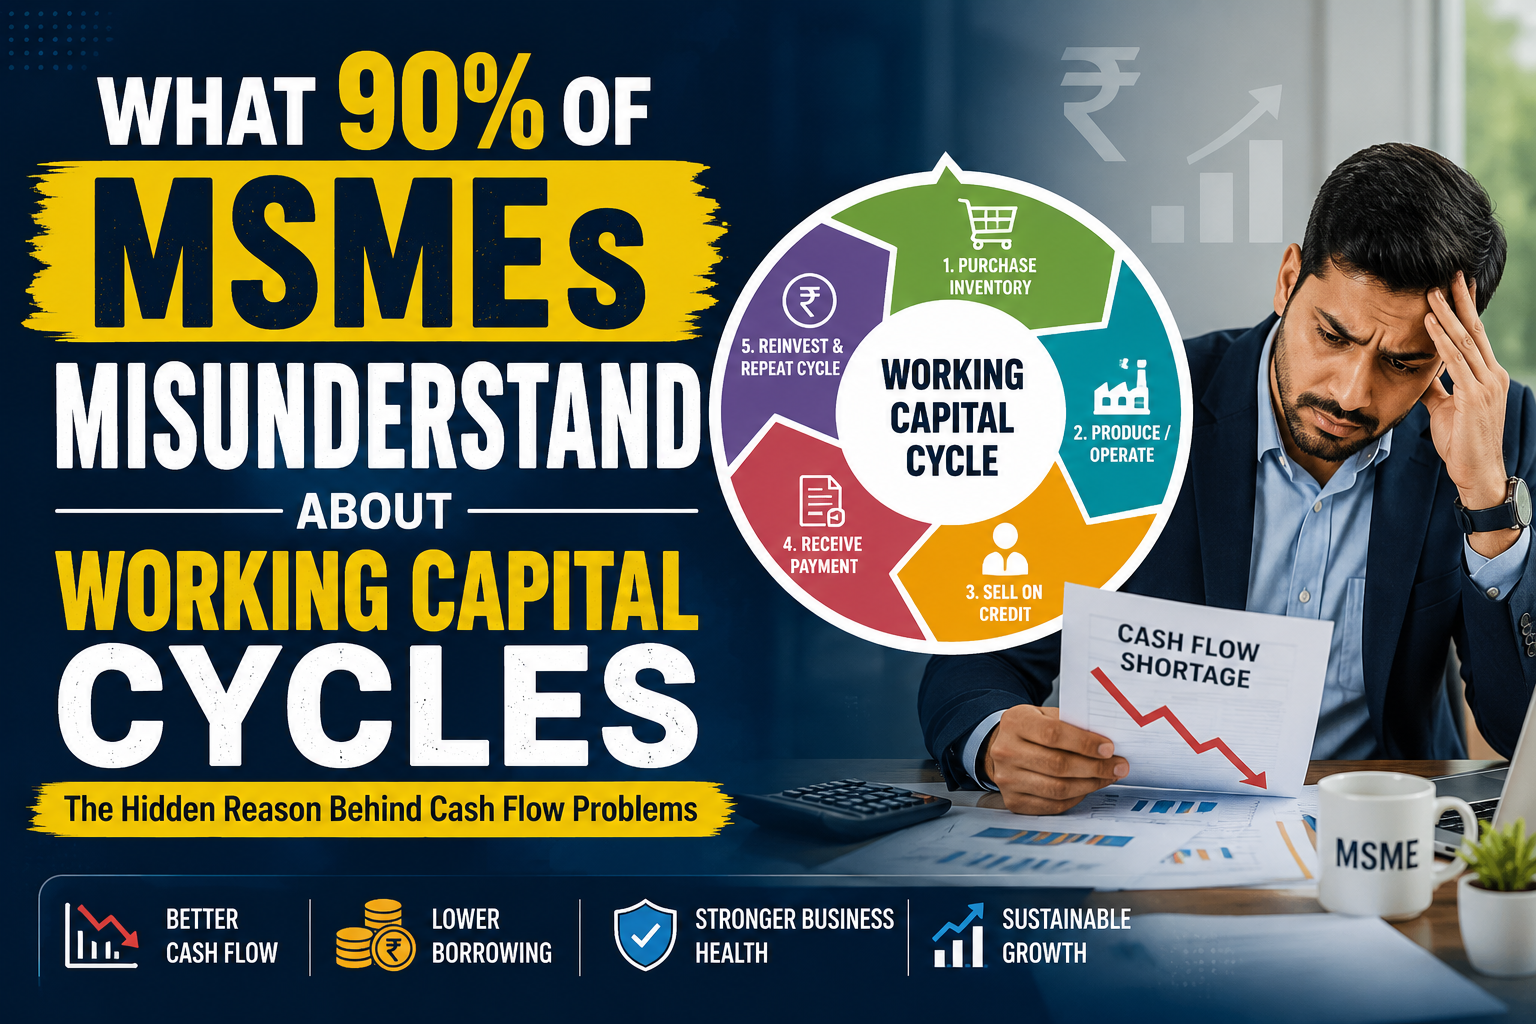
The working capital cycle refers to the time taken between:
Spending money on operations and inventory, and
Receiving money back from customers.
The shorter this cycle is, the healthier the business becomes.
The longer cash remains stuck in inventory or unpaid invoices, the greater the financial pressure on the business.
The Biggest Misunderstanding: “Sales Growth Means Financial Health”
One of the most common mistakes MSMEs make is believing that growing sales automatically improve cash flow.
In reality, rapid growth can sometimes create even bigger financial stress.
For example:
A business receives large orders
More raw materials are purchased
Production increases
Credit is given to customers
Payments are delayed for 60–90 days
During this period, the MSME must continue paying:
Employees
Vendors
Utility bills
Transportation costs
Loan repayments
Even though the company appears profitable, actual cash remains blocked.
This is why many MSMEs experience a paradox:
“Business is growing, but cash problems are increasing.”
Why MSMEs Struggle With Working Capital Cycles
1. Excessive Dependence on Customer Credit
Many MSMEs offer long credit periods to retain customers or compete in the market.
While this may increase sales temporarily, delayed receivables create severe liquidity stress.
Large buyers often negotiate:
60-day payments
90-day payments
Sometimes even 120-day cycles
For small businesses, surviving during this waiting period becomes difficult.
The result:
Borrowing increases
Interest costs rise
Profit margins shrink
2. Inventory Mismanagement
Inventory is often treated as an asset, but excess inventory can silently damage cash flow.
Unsold stock means:
Cash is blocked
Storage costs increase
Product aging risk rises
Operational efficiency declines
Many MSMEs over-purchase due to:
Fear of stock shortages
Supplier discounts
Poor demand forecasting
However, smart businesses focus on inventory turnover, not inventory accumulation.
3. Confusing Profit With Cash
This is one of the most dangerous financial misunderstandings.
A business may show:
Strong revenues
High profit margins
Positive balance sheets
But if customers have not paid yet, the business may still face a cash crisis.
Cash flow determines survival.
Profit determines long-term sustainability.
Both are important — but cash comes first.
4. Lack of Financial Planning
Many MSMEs operate reactively rather than strategically.
Instead of forecasting:
Upcoming expenses
Receivable timelines
Seasonal fluctuations
Vendor obligations
Businesses often depend on last-minute borrowing.
This creates:
Higher debt dependence
Emergency financial stress
Weak negotiation power with lenders
The Real Impact of Poor Working Capital Management
Poor working capital cycles affect much more than daily cash flow.
They directly impact:
Business growth
Creditworthiness
Supplier relationships
Employee confidence
Operational stability
In severe cases, even profitable MSMEs can shut down because they cannot manage short-term liquidity.
This is why investors and lenders closely examine:
Receivable cycles
Inventory turnover
Cash conversion efficiency
Operational liquidity
Not just profit statements.
What Smart MSMEs Do Differently
The MSMEs that thrive in today’s economy understand that liquidity management is a strategic advantage.
Here’s what successful businesses focus on:
1. Monitoring Cash Flow Weekly
Instead of reviewing finances only monthly or quarterly, successful MSMEs track:
Incoming payments
Upcoming expenses
Outstanding invoices
Inventory movement
Regular monitoring prevents financial surprises.
2. Reducing Receivable Delays
Leading MSMEs improve collections by:
Setting clear payment terms
Sending automated reminders
Offering early payment incentives
Digitizing invoicing systems
Faster collections improve liquidity immediately.
3. Optimizing Inventory
Smart businesses maintain balanced inventory levels based on:
Demand forecasting
Seasonal trends
Sales velocity
The goal is not “more stock,” but “efficient stock movement.”
4. Using the Right Financial Products
Modern MSMEs are increasingly using:
Invoice financing
Working capital loans
Supply chain financing
Digital lending platforms
These solutions help businesses maintain operational continuity without disrupting growth.
Platforms like MSME Bharat Manch are helping MSMEs explore multiple financial solutions and improve financial awareness in a structured manner.
Technology is Changing Working Capital Management
The next generation of MSMEs is becoming more data-driven.
Digital tools now help businesses:
Track receivables in real time
Forecast cash flow
Monitor inventory movement
Automate accounting
Improve payment collection cycles
Businesses adopting financial technology early are gaining:
Better visibility
Faster decision-making
Improved lender confidence
Stronger operational control
In the coming years, financial discipline and digital visibility will become key competitive advantages for MSMEs.
The Future Belongs to Financially Aware MSMEs
The biggest shift happening in the MSME sector is not just digital transformation — it is financial awareness.
Businesses are slowly realizing that:
Growth without liquidity is risky.
Sustainable MSMEs are not necessarily the ones generating the highest revenue.
They are the ones managing:
Cash efficiently
Credit carefully
Inventory intelligently
Financial planning proactively
The next decade will reward MSMEs that combine ambition with financial discipline.
Conclusion
Working capital is not just an accounting concept — it is the operational heartbeat of every MSME.
Unfortunately, many businesses still focus only on sales and profits while ignoring the movement of cash within the business cycle.
This misunderstanding creates unnecessary financial stress, borrowing pressure, and growth limitations.
The MSMEs that will thrive in the future are those that:
Understand cash flow deeply
Build efficient working capital systems
Use modern financial tools wisely
Plan proactively instead of reacting under pressure
Because in business, survival is not determined by how much you sell.
It is determined by how efficiently you manage the cash behind those sales.